Having a million dollars saved for retirement sounds like the answer to almost every financial worry.
But a large bank balance does not automatically bring happiness, good health, close friendships, or a satisfying daily life. Some wealthy retirees still struggle with loneliness, stress, and the feeling that their best years are behind them.
Brett wanted to look beyond the numbers and explore what makes retirement genuinely comfortable. His focus was on the everyday habits that help financially secure older adults protect their money, independence, relationships, and sense of purpose.
What stood out was how ordinary many of these habits were. They were less about luxury purchases and more about decisions that could be repeated week after week.
1. They Keep Their Everyday Lifestyle Surprisingly Simple
One of the first ideas that caught Brett’s attention was the difference between having wealth and feeling the need to display it. A comfortable retirement does not require a large house, an expensive vehicle, or constant upgrades to prove that someone has succeeded.
Many financially secure retirees understand that every major purchase creates responsibilities. A bigger home means more maintenance, higher insurance costs, property taxes, and possibly more work than they want to manage.
Brett saw a useful principle in choosing comfort over appearance. A manageable home, reliable transportation, and familiar routines can offer more freedom than expensive possessions that require constant attention.
The goal is not to live cheaply or avoid enjoying money. It is to spend on things that improve daily life while refusing expenses that add little lasting satisfaction.
2. They Treat Financial Security as More Important Than Showing Wealth
A retirement account worth a million dollars can still create anxiety when spending is uncontrolled. Brett recognized that the real benefit of wealth is having enough financial room to handle ordinary life without constantly worrying about the next bill.
That requires more than watching investment balances rise and fall. Retirees also need to consider housing expenses, health costs, taxes, transportation, and how their income will support them over many years.
Brett’s takeaway was that a financially comfortable person often thinks about what their money needs to accomplish. Instead of asking how much more they can buy, they ask how much security their savings can provide.
A large portfolio is useful, but predictable living costs and realistic spending decisions are what help make that portfolio feel dependable.
| Financial Habit | How It Supports Retirement |
|---|---|
| Keeping housing costs manageable | Leaves more money for other needs |
| Reviewing monthly expenses | Makes rising costs easier to notice |
| Maintaining emergency savings | Reduces pressure during unexpected events |
| Planning for health expenses | Helps prepare for future care needs |
| Avoiding unnecessary debt | Keeps more retirement income available |
These habits are useful even for someone who has never earned a large salary. Brett’s larger lesson was that financial confidence depends partly on how well resources match the life a person wants to live.
3. They Protect Their Health Before Problems Become Bigger
Brett could see why physical independence deserves a place beside financial security. A person may have plenty of money but still find retirement frustrating when walking, shopping, climbing stairs, or enjoying favorite activities becomes difficult.
Regular movement can help older adults maintain strength, balance, and everyday function. Walking, gardening, swimming, and appropriate strength exercises can all fit into a healthy retirement routine.
The key is finding activities that match a person’s abilities and health conditions. Someone using a cane, walker, or wheelchair can still maintain an active, fulfilling life with suitable support.
For adults age 65 and older, general CDC guidance recommends at least 150 minutes of moderate aerobic activity each week, muscle strengthening on two days, and balance activities. People who cannot meet those targets can still benefit from activity suited to their abilities.
Brett’s lesson was to protect the physical abilities that make ordinary choices possible. Regular checkups, addressing new symptoms, and making safe adjustments at home can be just as valuable as an exercise routine.
4. They Maintain a Small Circle of Dependable Friends
Money can pay for travel, entertainment, and a comfortable home. It cannot guarantee that someone will answer the phone when a retiree feels lonely or needs a person to talk with.
Brett found this distinction especially meaningful because retirement changes social life. Former coworkers may disappear from daily routines, friends may relocate, and some relationships slowly fade without regular contact.
A strong social circle does not need to include dozens of people. Even one or two dependable friends can provide companionship, emotional support, and the reassurance that someone genuinely cares.
Brett’s lesson was to treat relationships as something worth maintaining rather than something that will always be there. Regular lunches, phone calls, shared hobbies, and simple invitations can help friendships remain part of everyday life.
He also recognized that living alone is not the same as being lonely. Some older adults enjoy living independently while maintaining meaningful connections with people they trust.
5. They Choose a Home That Makes Retirement Easier
A large family house may represent decades of work and cherished memories. But the same property can become expensive, exhausting, or difficult to manage as someone gets older.
Brett noticed how important housing decisions are to retirement comfort. Stairs, yard maintenance, property taxes, long drives, and unexpected repairs can gradually turn a once comfortable home into a source of stress.
The better choice is not always downsizing. Some retirees remain happiest in familiar homes after making practical improvements, while others prefer smaller apartments, condominiums, or communities closer to services and friends.
The important factors are safety, affordability, access, and a genuine sense of belonging. Homeownership can provide stability, but renting a suitable home can also offer security and freedom.
Brett’s takeaway was simple: a retirement home should support the way someone wants to live now. It should not become an obligation maintained only because it once represented success.
6. They Always Have Something Worth Getting Up For
One of retirement’s unexpected challenges is losing the structure that work once provided. A person may spend decades following schedules, solving problems, and feeling useful, only to discover that retirement leaves those responsibilities behind.
Brett became interested in the value of having a reason to begin each day. Without meaningful activity, even a comfortable life can start to feel repetitive and disconnected.
Purpose does not need to involve earning money or accomplishing something impressive. It might come from volunteering, caring for a pet, helping family members, gardening, mentoring, woodworking, or learning a new skill.
The important part is having something that creates interest and a sense of contribution. A person who feels useful may find more satisfaction in an ordinary Tuesday than someone waiting for the next expensive vacation.
Brett’s lesson was that retirement works better when it includes activities that matter personally. Financial freedom creates opportunities, but a meaningful routine helps turn those opportunities into a satisfying life.
7. They Build a Weekly Routine Without Making Retirement Feel Like Work
The freedom to wake up without an alarm is one of retirement’s greatest pleasures. Yet having every day completely open can sometimes make weeks feel strangely similar.
Brett recognized that a simple weekly rhythm can help retirees stay physically active, socially connected, and mentally engaged. Structure creates reasons to leave home, meet people, and continue enjoyable activities.
The strongest routines leave room for rest and unexpected opportunities. Retirement should not feel like another demanding job, but it can benefit from a few dependable commitments.
| Day | Simple Retirement Habit | Possible Benefit |
|---|---|---|
| Monday | Walk or exercise with a friend | Movement and connection |
| Tuesday | Work on a hobby or personal project | Purpose and enjoyment |
| Wednesday | Review household tasks and finances | Better organization |
| Thursday | Attend a group activity | Social connection |
| Friday | Spend time with family or friends | Stronger relationships |
| Saturday | Visit somewhere enjoyable | Variety and anticipation |
| Sunday | Rest and plan the coming week | Balance and flexibility |
Brett liked the idea of treating routines as anchors rather than strict rules. A weekly activity gives the day some shape, but retirees should still feel free to change plans when something better comes along.
The goal is to make ordinary weeks feel worthwhile. Small activities repeated consistently can offer satisfaction without requiring major spending.
8. They Spend Money on Experiences That Matter to Them
Brett’s exploration raised an interesting question about retirement spending. Once basic needs are covered and financial security is reasonably protected, what purchases actually make life feel better?
An expensive object may be exciting when it is new, but that excitement can fade. Time with loved ones, a favorite hobby, or a meaningful experience may continue to provide pleasant memories long afterward.
That does not mean every retiree needs to travel internationally or book costly vacations. Some people find just as much satisfaction in local trips, family meals, community events, or afternoons spent doing something they love.
The best spending choices depend on personal interests, health, and budget. A person who enjoys gardening may value better tools and plants more than a luxury hotel, while someone who loves visiting family may prioritize transportation.
Brett’s takeaway was to connect spending with personal enjoyment rather than social expectations. Money becomes more useful when it supports a life that feels good to the person living it.
9. They Stay Involved With Family Without Trying to Control Everyone
Family relationships can bring some of retirement’s most rewarding moments. But Brett recognized that healthy family connections often require respect, boundaries, and the willingness to let other adults make their own decisions.
Retired parents may have more available time than their grown children. When those different schedules create mismatched expectations, disappointment can grow unless both sides communicate clearly.
A meaningful relationship is not measured only by how often someone visits or calls. The quality of conversations, mutual respect, and the feeling of being welcomed can matter more than constant contact.
Brett also understood that family means different things to different people. Older adults without children or close biological relatives can build supportive relationships through friends, neighbors, community groups, and other people who become chosen family.
The habit worth keeping is making room for genuine connection without demanding it. Regular invitations, thoughtful messages, and respectful boundaries can allow relationships to stay warm while preserving everyone’s independence.
10. They Keep Control Over as Many Daily Decisions as Possible
Brett was struck by how much freedom depends on small everyday choices. Being able to decide when to wake up, what to eat, whom to visit, and how to spend an afternoon can make retirement feel personal and satisfying.
That control can become harder when health problems, transportation limits, financial pressure, or housing difficulties begin deciding the day’s schedule. Even relatively small restrictions may feel frustrating when they affect activities a person values.
The habit Brett valued was adapting early instead of automatically giving up an activity. Using grocery delivery, arranging rides, installing bathroom safety features, or accepting help with heavy chores may protect independence.
Accepting assistance does not mean losing control. In many cases, the right support allows an older adult to continue making decisions that matter.
Brett believed the useful question is not whether someone can do everything without help. It is whether they still have a meaningful say in how their life is lived.
11. They Stay Curious and Continue Learning
Retirement may end a career, but it does not have to end personal growth. Brett saw curiosity as a practical way to keep days interesting when familiar work responsibilities are gone.
Learning can take many forms, including reading, studying history, trying new recipes, practicing photography, or developing a hobby. Some retirees enjoy community classes, while others prefer learning privately at home.
The goal does not need to be mastering a difficult skill or achieving a particular result. The pleasure may come from discovering something unfamiliar and having a new topic to discuss with others.
Brett recognized that enjoyable learning can also create opportunities for social interaction. A gardening group, book club, language class, or local workshop can introduce retirees to people who share their interests.
The lasting habit is remaining open to new experiences without feeling pressure to compete. Curiosity gives retirement more variety and reminds people that meaningful interests can develop at any age.
12. They Deal With Small Problems Before Those Problems Take Away Freedom
Brett considered how easily a manageable concern can become a major retirement problem when ignored. A difficult staircase, growing financial pressure, an unreliable vehicle, or a weakening friendship may seem unimportant until it begins interfering with daily life.
Addressing concerns early can leave more options available. A home modification may prevent some difficulties, a budget review may reveal rising expenses, and a conversation may help repair a relationship before distance grows.
This does not mean every problem can be prevented. Illness, bereavement, market downturns, and unexpected family needs can change retirement even when someone plans carefully.
The habit is to pay attention to changes instead of assuming they will correct themselves. Brett saw value in regularly asking which part of daily life is becoming harder and what realistic step might help.
| Area | Early Warning Sign | Practical Response |
|---|---|---|
| Finances | Savings are being used faster than planned | Review spending and retirement income |
| Housing | Maintenance is becoming overwhelming | Arrange help or consider alternatives |
| Health | Daily movement is getting harder | Seek appropriate medical guidance |
| Social life | Weeks pass without meaningful contact | Arrange regular conversations or activities |
| Transportation | Driving or travel becomes difficult | Explore reliable alternatives |
| Daily purpose | Most days feel empty | Schedule one enjoyable commitment |
Brett’s lesson was that financial resources are most useful when people use them to solve real problems. Paying for suitable help, adjusting routines, or changing living arrangements can sometimes preserve more freedom than holding onto every dollar.
13. They Always Keep Something on the Calendar to Look Forward To
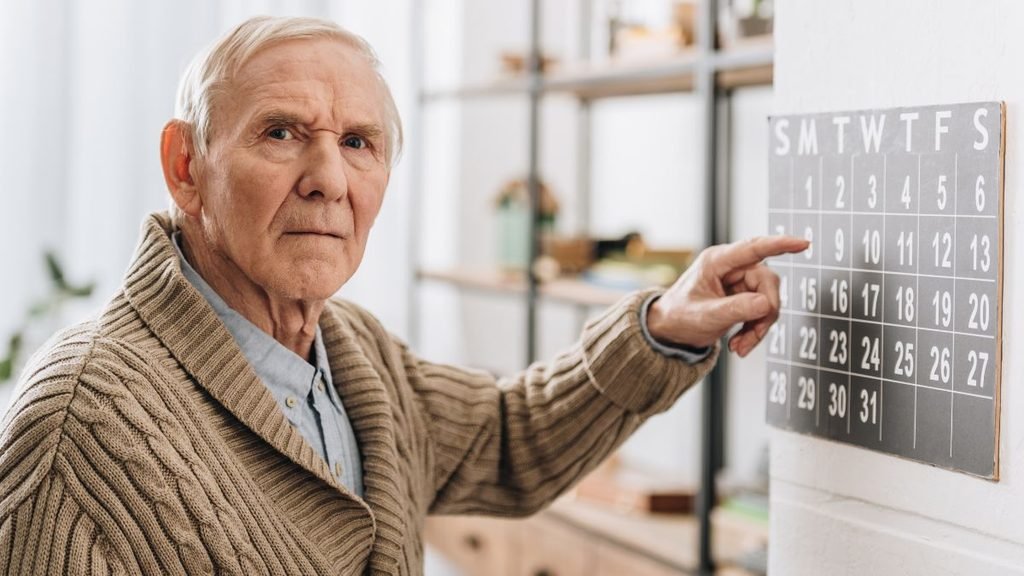
The final habit Brett found meaningful had little to do with investments or expensive purchases. It involved having something in the future that made the next few days or weeks feel interesting.
Retirement removes many of life’s automatic milestones. Promotions, business deadlines, school schedules, and major career goals may disappear, leaving some people without events that create anticipation.
A future plan does not need to be impressive. It might be a family birthday, a weekly breakfast with friends, a fishing trip, a garden project, or tickets to a local event.
These small plans give ordinary weeks direction. They can also encourage retirees to stay connected, maintain useful routines, and participate in activities they enjoy.
Brett saw this habit as a reminder that retirement should not become a period of simply passing time. Having something worth anticipating can help people remain interested in the years ahead.
What Brett Learned About Money and Happiness After Retirement
The central idea running through these 13 habits is that financial wealth and retirement satisfaction are related, but they are not identical.
Money can make it easier to afford secure housing, health care, transportation, and enjoyable activities, yet it cannot guarantee meaningful relationships or a sense of purpose.
Brett’s focus was on how retirement resources support daily life. A large savings balance can create choices, but those choices matter most when people know what they want their retirement to include.
Consider how differently two financially comfortable retirees might live. One could spend heavily on possessions while feeling isolated and overwhelmed, while another might prefer simpler surroundings, dependable friendships, and meaningful weekly activities.
Neither person’s happiness can be determined from a bank statement alone. Personal health, family circumstances, personality, past experiences, and unexpected events all influence how retirement feels.
The 13 Habits at a Glance
| Habit | What It Helps Protect |
|---|---|
| Living simply | Financial flexibility |
| Prioritizing financial security | Peace of mind |
| Staying physically active | Daily function |
| Maintaining friendships | Emotional support |
| Choosing manageable housing | Comfort and safety |
| Having a sense of purpose | Meaningful days |
| Keeping a weekly routine | Structure and balance |
| Spending on meaningful experiences | Personal enjoyment |
| Maintaining family connections | Belonging |
| Preserving daily choices | Independence |
| Continuing to learn | Curiosity and engagement |
| Addressing problems early | Future options |
| Looking forward to future events | Anticipation and interest |
The value of these habits is that most can be adapted to different financial situations. Someone with a modest retirement income may still strengthen friendships, develop routines, pursue hobbies, and make realistic plans for the future.
At the same time, money should not be dismissed as unimportant. People struggling to afford food, medicine, housing, or other basic needs face pressures that positive habits alone cannot solve.